Executive summary
Cedar & Saffron is a fictional Mediterranean restaurant proposed for Austin, Texas. This example shows how an operating story, a saved financial forecast and a ten-slide pitch fit together. The figures describe a planning scenario, not the performance of an existing restaurant.
Business overview
Cedar & Saffron would serve bowls, warm pitas and office catering from one 1,800 sq ft second-generation restaurant with 32 seats. A short menu shares ingredients across counter orders and catering. The proposed customer is a nearby worker or resident who wants a complete meal through counter service or direct pickup. The fictional founder, Maya Ellis, works as general manager; owner compensation is already included in payroll.
Key priorities
The first priority is to validate repeat lunch demand before signing an unconditional lease. The proposed team would test recipes, complete supplier costing and run paid pop-up lunches, then assess a small number of viable restaurant sites. Opening is modeled for January 2027 after a proposed 12-week preparation period. Sales ramp over four operating months. A second location is outside this plan.
Financial highlights
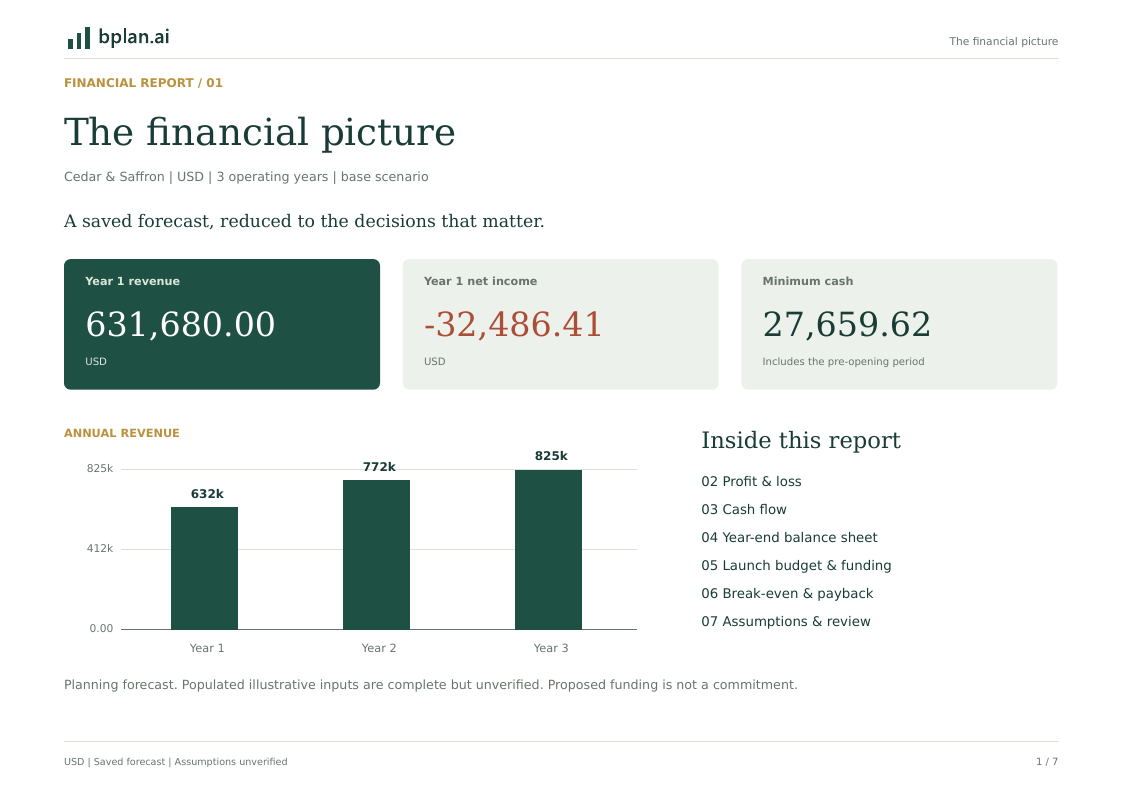
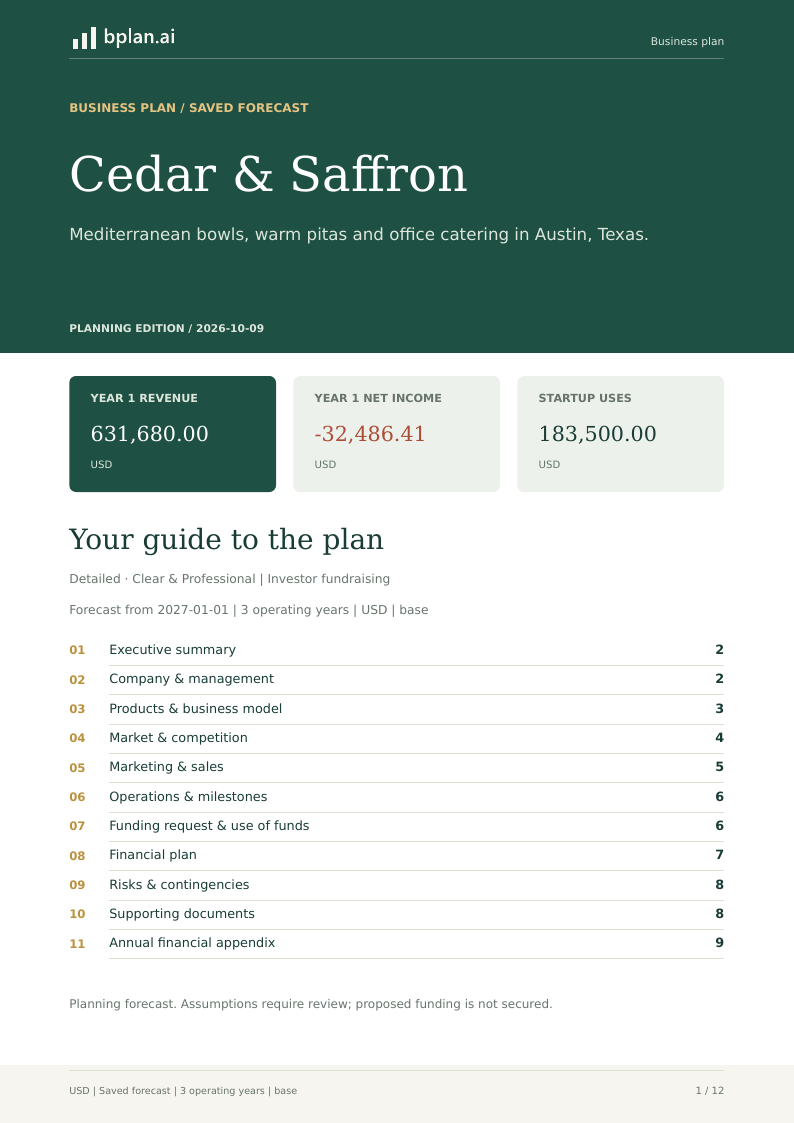
The saved base case proposes $250,000.00 of combined equity. Startup spending is $183,500.00, leaving $66,500.00 of opening cash. First-year revenue is $631,680.00 and first-year net income is -$32,486.41. Operating EBITDA becomes positive in month 4; minimum modeled cash is $27,659.62. Pre-tax project payback is not reached within the 36-month forecast.
- Can paid tests support the target volume at the modeled price?
Company & management
The company is presented as an independent, single-location prelaunch venture. The scenario is deliberately narrow enough to connect daily operating decisions to one financial model.
Company background
The fictional business would operate in Central Austin, within the City of Austin jurisdiction. No specific address, lease, entity registration or permit is claimed. The assumed second-generation premises already have a restaurant shell; a site needing a new hood, grease interceptor, major plumbing or structural changes would require a revised budget. The planning currency is USD and the first operating month is January 2027.
Ownership & management
Maya Ellis is an invented working founder used to make the example concrete. The scenario assumes six years of kitchen and counter-service experience, including shift scheduling and purchasing. This is a fictional biography, not an independently verified credential. Maya would own the operating decisions, supplier approval, staffing and cash review. An outside equity partner is proposed, but ownership percentages, valuation, distributions and governance terms have not been specified.
Team & responsibilities
The budget includes a working owner/general manager, one lead cook, one line cook, two full-time counter staff and one part-time prep/dish role. Cooks and counter staff are modeled at 40 paid hours per week; prep/dish at 20. The owner plans to work about 45 hours per week. The 15% employer-cost allowance is added once to each role. The team would stagger shifts around lunch and early dinner; the schedule needs a detailed coverage check before hiring.
- What entity and investment terms will be adopted?
- Does a detailed shift plan cover breaks, absence and preparation time?
Products & business model
The offer combines a focused everyday menu with preordered office meals. These are two separately modeled revenue streams served from the same kitchen.
Products & services
The proposed menu has chicken, falafel and roasted-vegetable bowls, warm pitas, hummus, a small set of sides and non-alcoholic drinks. Ingredients overlap across recipes to keep purchasing and preparation manageable. Signature combinations make ordering quick; a limited build-your-own option accommodates preferences. Catering uses the same recipes, with labeled portions and pickup or local delivery arranged in advance. No alcohol or third-party delivery platform is included.
Pricing & revenue streams
The counter stream assumes 130 transactions per open day at an average realized basket of $17.00, excluding customer sales tax. The restaurant is modeled as open 26 days per month, with capacity for 200 counter transactions per day. Catering assumes 5 events per month with 30 paid meals per event at $18.00 per meal when the four-month ramp is complete. These inputs produce $60,160.00 of combined monthly revenue in month 4, directly from the saved forecast.
Customer value
The proposed value is a dependable, clearly priced meal with direct ordering and familiar options for office groups. A compact menu should make recipe costing, portion control and staff training easier. These benefits are hypotheses to test with paying customers. The financial case does not assume that menu variety, branding or positive feedback alone will produce the required daily volume.
- Which recipes and basket mix sustain margin at the assumed average price?
Market & competition
Austin is the proposed location, but this plan does not claim a measured local market size or established customer traction. Published market context is separated from the demand assumptions.
Target customers
The initial segments are nearby workers buying weekday lunch, residents buying an early dinner or pickup meal and office administrators arranging group lunches. The proposed catchment is a short trip from the eventual site, rather than the whole Austin metropolitan area. Customer interviews should identify buying frequency, acceptable total spend, pickup timing and alternatives. The owner should select a site only after checking visibility, access, parking or walkability against these specific buying occasions.
Demand & validation
The forecast target of 130 counter transactions per day has not been observed. Before a lease commitment, the proposed validation is a sequence of paid pop-up lunches and catering trials, with transaction records and customer follow-up. The test should measure actual basket value, ingredient cost, preparation time and repeat orders. Traffic counts and office introductions can support site selection, but neither is evidence of restaurant sales. No survey results, waitlist, advance orders or signed catering agreements are invented here.
Competition & positioning
Mediterranean bowl and pita concepts, including CAVA, establish a recognizable product category; other fast-casual lunch offers compete for the same meal occasion. Competitor pricing and market share are not assumed. Cedar & Saffron proposes a neighborhood focus and preordered office catering. A field review must compare the actual nearby alternatives, menu prices, service speed and pickup experience before claiming a competitive advantage.
- Which actual site has sufficient repeat lunch demand?
- What evidence would cause the owner to lower the sales target?
Marketing & sales
The saved model allocates $900.00 per month to local marketing in the first operating year. This is a spending allowance; no achieved acquisition cost or channel return is assumed.
Customer acquisition
The proposed launch channels are an accurate local-search listing, direct pickup ordering, introductions to nearby office administrators, paid sampling sessions and referrals. The owner would start with a limited number of channels and tag offers so that paid transactions can be linked to activity. Office visits should focus on a practical catering offer, lead time, portions and pickup arrangements. The team should track repeat buyers rather than treating social followers as customer demand.
Sales process
Counter customers would order and pay at the point of service or through a direct pickup system. Office catering would be confirmed in advance, with payment on or before collection. The cash forecast assumes zero collection days across both streams; extending invoice terms would require an explicit working-capital change. The 2.6% payment-processing allowance is modeled separately from food cost. Customer sales tax is excluded from revenue. No subscription, marketplace remittance or platform commission is inferred.
Retention & measurement
The proposed retention process is consistent food, accurate orders, a simple reorder link and follow-up with office buyers. The owner would review transactions by daypart, average basket, repeat orders, waste and catering conversion each week. A loyalty offer should be costed before introduction; discounts are currently zero in the model. Channel spending can be redirected after evidence appears, but a forecast improvement should not be claimed before the related input changes are saved.
- Which channels produce repeat paid orders within the spending allowance?
Operations & milestones
The proposed operating design uses one production kitchen, one counter and direct pickup, with catering prepared outside the most crowded counter periods.
Facilities & resources
The assumed 1,800 sq ft site has 32 seats and opens Monday-Saturday, 11 a.m.-8 p.m. Monthly base rent is $4,500.00, plus $750.00 NNN/CAM. This is a planning assumption, not a lease quote. Assets cover refurbishment, kitchen equipment, furniture, POS and signage. Ventilation, grease, power, accessibility and restrooms need site-specific review.
Service delivery
Daily work covers preparation, lunch assembly, restocking, dinner and closing checks. Seven days of modeled ingredient coverage supports purchasing; freshness determines actual stock levels. Counter throughput is capped at 200 transactions per open day across 26 open days: 5,200 transactions per month. The separate monthly supply ceiling is 6,500 transactions, so throughput is the tighter limit in this saved scenario. Requested counter demand is 130 transactions per day before the four-month ramp and later demand growth. Catering targets five 30-meal events; the shared kitchen schedule still needs an operating test.
Launch & development milestones
The illustrative 12-week preparation period starts with paid menu tests and site inspection, then conditional lease terms, contractor quotes, layout and permits, hiring and training. A soft opening precedes normal service. Pre-opening inspection and operating permits must be confirmed. Actual approvals and site work determine the opening date; the proposed schedule is not guaranteed.
- What work does the actual site require?
- Which permits, inspections and construction tasks determine the opening date?
Funding request & use of funds
The launch assumes proposed equity, without a loan or any secured funding.
Use of funds
Saved startup uses total $183,500.00: $157,000.00 assets, $22,000.00 expensed setup and $4,500.00 ingredients. Assets allow $75,000 refurbishment, $58,000 kitchen equipment, $18,000 furniture and $6,000 POS/signage. Setup allows $1,326 published Austin health fees, $10,500 pre-opening occupancy, $6,500 training/tests and $3,674 professional preparation. Deposits and extra site work need separate quotes.
Sources of funding
The saved equity input of $250,000.00 combines $80,000.00 proposed founder funding and $170,000.00 external equity. Both are assumed at month 0; neither is committed or received. These cash inflows are financing, not restaurant revenue or profit.
Owner contribution
The $80,000.00 owner contribution is fictional; available funds need confirmation. Founder salary is already in operating expenses and must not be added twice.
Funding request
The $170,000.00 external request plus owner funding leaves $66,500.00 opening cash. Minimum modeled cash is $27,659.62; the $0.00 unfunded gap applies only to this funded scenario. The request differs from that gap. Valuation, ownership, distributions and exit terms remain unspecified.
- Will both contributions be available before startup spending?
- How will actual investment and deposit terms affect cash?
Financial plan
One saved forecast covers January 2027-December 2029. Prelaunch month 0 appears separately in the reports.
Forecast assumptions
The four-month ramp targets 130 daily orders on 26 days at $17.00, plus 5 monthly 30-meal catering events at $18.00. Ingredients are 32.4% of sales (illustrative planning input); packaging adds 1.5% and processing 2.6%. Employer costs are 15%, stock and supplier terms seven days, collection zero days and tax provision 21%. The saved model retains every input and growth assumption.
Financial outlook
Revenue is $631,680.00, $771,523.92 and $824,616.72 in years 1-3; net income is -$32,486.41, $37,839.92 and $54,605.12. The first-year loss reflects the sales ramp with ongoing staffing costs. These years exclude $22,000.00 of prelaunch expense. Annual reports use the saved run, which retains all monthly rows.
Cash needs & financial resilience
Operating EBITDA turns positive in month 4. Month-4 operating break-even is $53,053.02 per month, excluding depreciation, interest and income tax. Minimum cash is $27,659.62; year-1 closing cash is $63,424.15. Depreciation and working-capital timing separate profit from cash. Pre-tax project payback is not reached within the 36-month horizon.
Debt & repayment
No loan, interest or principal repayments are modeled. Future borrowing requires actual terms and a new forecast; the current case establishes no lending approval or guaranteed return.
- Does paid testing support the sales mix and volume?
- What changes follow from actual supplier, rent, staffing and tax terms?
Risks & contingencies
The main risk is entering a fixed-cost lease and staffing commitment before proving sufficient repeat demand. The positive cash result depends on the full proposed funding contribution and the saved assumptions.
Key risks
A slower lunch ramp could absorb the opening cash buffer. Menu waste, packaging usage and ingredient-price changes could reduce the contribution margin. A site requiring major work could exceed the refurbishment allowance or delay opening. Shift gaps could increase labor cost or restrict service. Catering introduces coordination demands even though it shares recipes. The forecast also omits refundable deposits, third-party delivery, owner distributions and expansion; adding them requires explicit model inputs.
Contingency actions
The proposed response is a conditional site decision after paid tests, a limited menu with recipe costing, a written contractor scope and a weekly cash review. The owner should separately test weaker sales while holding payroll and fixed costs constant, then assess whether the cash reserve covers the result. Reducing the team, changing the site or raising prices are decisions to model and validate, not assumed automatic fixes. Expansion should wait for repeat demand and sufficient cash after the first site stabilizes.
- Which downside would cause the owner to postpone or redesign the launch?
Supporting documents
The available material is the fictional case description, its saved financial input/output, this business-plan text, the ten-slide pitch and its supporting planning notes. No actual business records are supplied.
Available supporting information
The package contains a detailed business-plan PDF, an independent financial-report PDF and a ten-slide pitch-deck PDF. All financial statements and linked pitch values share the same saved source. The planning basis is fictional and all funding remains proposed. Wages, equipment prices and demand require business-specific validation.
Documents to obtain
Before a real launch, obtain paid-test transaction records, supplier recipe and equipment quotes, a site inspection, a contractor scope, actual lease and deposit terms, a coverage-based staffing schedule, entity and tax advice, permit confirmations and funding documentation. Customer letters or catering orders should appear only if actually obtained. This example contains no permit certificate, signed contract, fabricated customer quote or proof of approved financing.
- Which actual evidence should replace each illustrative input before a commitment?