Executive summary
Juniper Table is a fictional single-site restaurant planning case in Austin, Texas. It demonstrates a complete business story, a saved native forecast and a ten-slide pitch. The decision is whether its particular sales mechanism and fixed commitments merit further paid testing, rather than whether restaurants in general are profitable.
Business overview
A neighborhood dinner restaurant with table service in Austin, Texas. Guests book or walk in for dinner. A cover is one guest served; an average bill of $42 excludes sales tax and tips. The target of 112 covers per open day represents 80 seats × two planned turns × 70% utilization. Nearby residents, couples and small groups buying a sit-down dinner.
Key priorities
Run paid trial dinners, record covers, check average food-only bills and time each service. Obtain a kitchen inspection, lease/deposit terms and a detailed shift roster before a site commitment. Opening is modeled for January 2027; permits, construction and hiring determine the real date. No paid traction, operating premises or founder track record is asserted.
Financial highlights
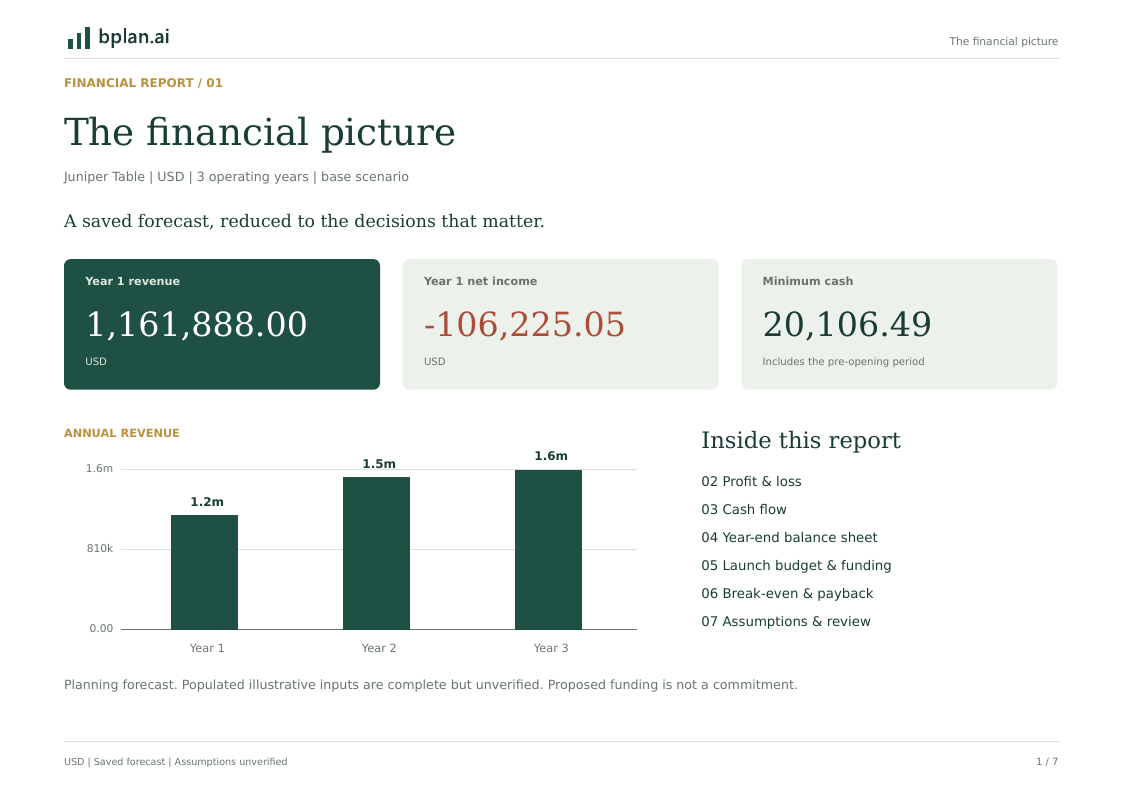
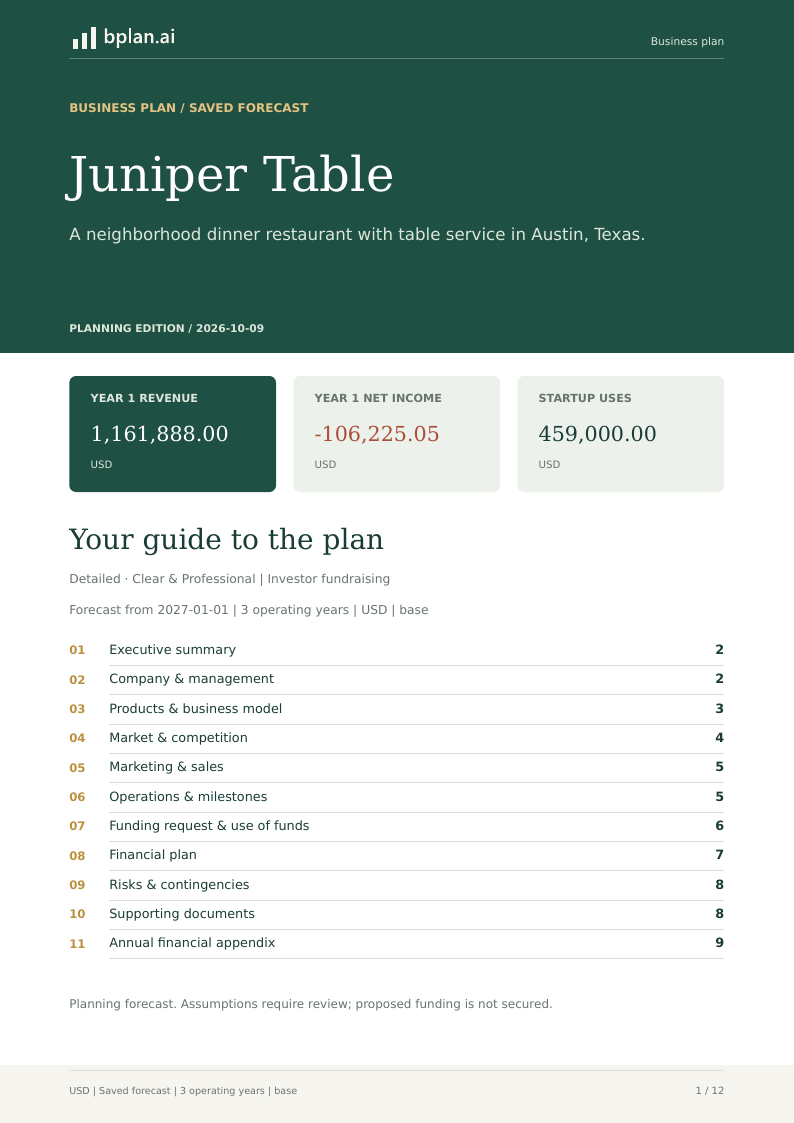
Proposed equity totals $600,000.00. Saved startup uses are $459,000.00, leaving $141,000.00 of opening cash. Year 1 revenue is $1,161,888.00 and net income is -$106,225.05. Minimum modeled cash is $20,106.49. Pre-tax project payback is not reached within 36 months.
- What paid evidence would support this specific format and sales target?
Company & management
The proposed business is independently operated at one site. A legal entity, signed lease and actual ownership agreement are not supplied. The fictional working-owner role makes responsibilities and compensation explicit without inventing a founder biography.
Company background
The scenario uses 3,200 sq ft of second-generation restaurant space and 80 dining seats. Tuesday–Sunday, dinner service. Geography is Austin, Texas, USA; there is no actual street address or inspected property. The premises assumption must be replaced if the chosen site has materially different ventilation, power, drainage or accessibility requirements.
Ownership & management
A working owner would approve purchasing, oversee the staff schedule and review cash each week. No name, professional qualification or restaurant experience is represented as real. The proposed external investment has no agreed valuation, ownership percentage, board rights or distribution policy. Those terms need separate documentation and advice before fundraising.
Team & responsibilities
Working owner / general manager: 1 × $6,000.00 per month, plus 15% employer allowance; Head chef: 1 × $6,000.00 per month, plus 15% employer allowance; Line cooks: 2 × $4,500.00 per month, plus 15% employer allowance; Servers — wages excluding tips: 4 × $3,000.00 per month, plus 15% employer allowance; Prep / dish: 2 × $2,800.00 per month, plus 15% employer allowance; Host / runner: 1 × $3,000.00 per month, plus 15% employer allowance. A host seats guests, servers take orders, the kitchen cooks to ticket and a runner coordinates the pass. The owner manages booking, staff coverage and the nightly close. Headcount is an annual planning input, not a completed roster. Verify coverage for preparation, breaks, rest days and absence; do not assume the owner can fill unlimited unpaid hours.
- Can a detailed roster cover all service and preparation hours within this payroll?
Products & business model
The offer is defined by the purchase occasion and the unit sold. Format-specific revenue inputs are preserved in the saved model rather than converted into one generic restaurant average.
Products & services
A compact dinner menu offers mains, sides, desserts and non-alcoholic drinks. Table service and the shared dining experience are part of the proposed offer. There is no modeled bar, private dining, takeaway stream or catering contract. Recipe overlap should reduce preparation complexity, but actual yield and waste require trials.
Pricing & revenue streams
Guests book or walk in for dinner. A cover is one guest served; an average bill of $42 excludes sales tax and tips. The target of 112 covers per open day represents 80 seats × two planned turns × 70% utilization. Dinner covers — full service: 112 per open day × 26 days × $42.00 at the end of a 6-month ramp. Daily capacity 160. Revenue is measured before customer sales tax and excludes tips. A target is constrained by the saved stream capacity; the forecast does not automatically turn every expression of interest into a sale.
Customer value
The proposed customer value is a dependable neighborhood dinner with attentive service and a clear food-only bill. Reservations should make the evening convenient without creating an unaffordable service promise. Validate willingness to pay with paid dinners and repeat bookings; positive comments alone do not establish sufficient covers.
- What menu mix and actual recipe cost support the intended contribution?
Market & competition
This example identifies a customer and buying occasion, but it does not claim a measured address-level market, local market share or unmet demand. A city population is not multiplied into invented restaurant sales.
Target customers
Nearby residents, couples and small groups buying a sit-down dinner. The eventual catchment must match travel time, purchase frequency and alternatives. Record who actually pays, who chooses the venue or channel and why that meal occasion matters. A target segment becomes useful evidence only when connected to paid behavior near the proposed operation.
Demand & validation
Run paid trial dinners, record covers, check average food-only bills and time each service. Obtain a kitchen inspection, lease/deposit terms and a detailed shift roster before a site commitment. Preserve transaction records, realized prices, repeat orders, waste and service times. Set the minimum evidence threshold before evaluating a site; weak results should reduce the sales input or stop the launch. Forecast ramp months do not substitute for a validation process.
Competition & positioning
Nearby independent dinner venues, casual dining chains and prepared meals at home compete for the same evening budget. Visit the actual neighborhood and compare food-only bill, booking availability, service time and ambience. A larger menu or attractive room does not establish a defensible advantage.
- Which paid signals would justify the volume at the eventual site?
Marketing & sales
Customer acquisition is a proposed operating process with a saved budget, not evidence of achieved channel return. The owner should connect activity to transactions and repeat purchasing before scaling spend.
Customer acquisition
Proposed channels are local discovery, accurate reservation listings, neighborhood introductions and paid preview dinners. The monthly local-marketing allowance is $1,500.00. Track reservations that become seated guests, the food-only bill and subsequent visits. Avoid counting social followers as dinner demand.
Sales process
Guests reserve or walk in, order during the visit and pay at the end of service. The saved model assumes zero collection days. Tips and customer sales tax are outside revenue; any gratuity administration, refund or additional processor terms require explicit review.
Retention & measurement
The proposed weekly review tracks repeat purchase, realized bill, complaints, refunds and contribution by buying occasion. Cost a discount before offering it; saved discounts and refunds are currently zero. Ask for feedback without inventing reviews, then revise the operating input when measured behavior supports the change.
- Which channel produces enough repeat contribution within the allowance?
Operations & milestones
The restaurant must deliver the planned volume with its actual kitchen, premises and paid team. Sales capacity and demand are separate inputs; a capacity ceiling is not a forecast that the kitchen will sell out.
Facilities & resources
The site assumption is 3,200 sq ft with 80 dining seats. Base rent is $9,000.00 plus $1,500.00 NNN/CAM per month. These are unquoted allowances. Second-generation premises refurbishment $190,000.00; Kitchen and refrigeration $140,000.00; Dining room furniture and fixtures $60,000.00; POS, booking hardware and signage $10,000.00. Inspect hood, grease handling, power, fire safety, access and building condition before confirming the work scope.
Service delivery
A host seats guests, servers take orders, the kitchen cooks to ticket and a runner coordinates the pass. The owner manages booking, staff coverage and the nightly close. Table turns and kitchen throughput must both support the covers target. Extra demand cannot be served by adding seats in the forecast alone. The model uses seven inventory days and seven supplier-payment days. Perishable stock still needs recipe-level purchasing and waste control; a modeled stock target does not establish safe food handling or supplier availability.
Launch & development milestones
The proposed sequence is paid menu testing, site inspection, conditional commercial terms, contractor and equipment quotes, permit review, hiring, training and a controlled soft opening. January 2027 is the modeled first operating month, not an approval promise. Do not compress permit or site-work dependencies merely to fit the forecast start date.
- Which site condition, approval or staffing gap could delay opening?
Funding request & use of funds
The funding scenario uses equity at prelaunch month 0, without debt. Proposed financing is kept separate from sales revenue and project profitability.
Use of funds
Saved startup uses total $459,000.00: $400,000.00 assets, $50,000.00 expensed setup and $9,000.00 opening stock. Second-generation premises refurbishment $190,000.00; Kitchen and refrigeration $140,000.00; Dining room furniture and fixtures $60,000.00; POS, booking hardware and signage $10,000.00. Setup is an illustrative allowance for pre-opening occupancy, training, professional preparation and permissions. It is not an itemized quote or a promise that all site costs fit.
Sources of funding
The financialModel equity input is $600,000.00, comprising $180,000.00 proposed owner funding and $420,000.00 proposed external equity. Neither contribution is secured. The saved model assumes both are available before launch spending; later or partial contributions require a new cash scenario.
Owner contribution
The working owner contribution of $180,000.00 is fictional and must be verified for a real launch. Owner compensation is already included in payroll. Work contributed by the founder does not automatically pay a contractor invoice or provide the same liquidity as contributed cash.
Funding request
The external request is $420,000.00. Combined proposed funding leaves $141,000.00 opening cash. This is an operating reserve and unallocated contingency, not an extra startup expense. The saved funding gap is $0.00 in this particular funded scenario; a request and a gap are different measures.
- Are contributions available when deposits, setup and equipment payments fall due?
Financial plan
The native saved forecast covers 36 operating months, January 2027–December 2029, with prelaunch separately reported. All document and page amounts use this exact saved run.
Forecast assumptions
Dinner covers — full service: 112 per open day × 26 days × $42.00 at the end of a 6-month ramp. Daily capacity 160. A larger dining room and staffed service shift create fixed commitments before the sales ramp is complete. No alcohol license, bar margin, tip income or events are assumed. Working-owner pay is included; employer costs add 15%. The flat 21% income-tax provision is a simplified input, not a tax opinion. Prices grow 2% annually; units grow 3% annually subject to capacity. Fixed costs and wages grow 3% annually.
Financial outlook
Year 1: revenue $1,161,888.00, EBITDA -$30,805.22, net income -$106,225.05, closing cash $106,108.28. Year 2: revenue $1,541,910.96, EBITDA $194,009.28, net income $104,023.98, closing cash $272,465.60. Year 3: revenue $1,619,931.72, EBITDA $220,602.72, net income $125,032.79, closing cash $459,831.72. EBITDA excludes depreciation, interest and income tax; net income includes the saved depreciation and tax provision. The operating years exclude prelaunch setup expense. A first-year result must be interpreted with the ramp and paid team intact.
Cash needs & financial resilience
The lowest modeled cash balance is $20,106.49. The saved funding gap is $0.00. First positive operating EBITDA occurs in month 5. Pre-tax project payback is not reached within 36 months. Cash differs from net income because of launch assets, depreciation, working capital and financing. Inspect the full cash-flow and balance-sheet reports before deciding the reserve is sufficient.
Debt & repayment
No loan draw, interest, principal repayment or lending approval is modeled. Adding debt requires its actual amount, draw date, interest rate and repayment terms in financialModel. The current equity-only forecast establishes neither bank affordability nor investor return. Project payback is a pre-tax operating measure, not a shareholder distribution schedule.
- Does the downside still have enough cash after all required site costs are included?
Risks & contingencies
The main risks follow from the chosen format, rather than from a generic list of restaurant challenges. The cash result depends on both the operating inputs and the full proposed equity arriving at prelaunch.
Key risks
Table turns and kitchen throughput must both support the covers target. Extra demand cannot be served by adding seats in the forecast alone. A larger dining room and staffed service shift create fixed commitments before the sales ramp is complete. No alcohol license, bar margin, tip income or events are assumed. No alcohol, third-party delivery, catering, debt, owner distributions, refundable lease deposits or second location. Add missing site requirements and deposits before treating this as a funding budget. Demand could ramp more slowly, recipes could waste more stock and staff coverage could cost more than assumed. Model omissions remain omissions even where the base case reconciles arithmetically.
Contingency actions
Make the site decision conditional on paid dinner tests, a written work scope and a coverage-based roster. Recalculate lower covers with wages and rent unchanged, then inspect the cash low point. If the reserve becomes inadequate, reduce commitments or postpone the launch; do not assume price increases or staff cuts are costless.
- Which measured signal would cause the owner to redesign or postpone?
Supporting documents
The supplied material is the fictional operating specification, one saved financial run, this complete plan and the ten-slide pitch. No lease, vendor quote, permit, tax opinion or signed investment document is supplied.
Available supporting information
The delivered package includes the business-plan PDF with native annual financial appendix, seven-section financial-report PDF and ten-slide pitch-deck PDF. Their totals share one financialModel and saved calculation identity. The website displays actual PDF interiors and provides the complete files for inspection. Generated scene illustrations are conceptual, not photographs of premises.
Documents to obtain
Obtain paid-test records, recipe and packaging costs, equipment and refurbishment quotes, a premises inspection, actual lease and refundable-deposit terms, shift coverage, supplier and channel contracts, applicable permissions, entity/tax advice and funding commitments. Add each material change to the model, save a new run and regenerate all dependent documents together.
- Which missing evidence changes the decision before any money is committed?