
THE COMPLETE BUSINESS PLAN
A specific operating decision.
Can completed key-service jobs support two paid technicians, stocked parts and owner dispatch without assuming universal vehicle coverage?
Fictional editorial scenario. Prices, workload, wages, costs and financing are illustrative planning inputs, not current quotes, measured local averages or actual company results.
The forecast shows a net loss in Year 1, Year 2, Year 3. Positive funded cash assumes the full proposed equity is received; it does not establish commercial viability.
01 / THE PLAN
Executive summary
Clover Auto Keys proposes a two-van mainstream vehicle key service in Nashville, Tennessee, USA. A proposed two-van automotive locksmith performing authorized compatible-vehicle lock, key and ignition tasks. The central launch decision is: Can completed key-service jobs support two paid technicians, stocked parts and owner dispatch without assuming universal vehicle coverage?
Business overview
Vehicle owners and authorized agents with a mainstream compatible vehicle, a defined task and an agreed payer. Two equipped vans share one completed-job slot pool. Lockouts, mechanical keys, transponder keys, smart keys and ignition repairs allocate expected jobs once; owner dispatch is support rather than another service van. The business will accept assignments within this service boundary and quote separately or refer work that falls outside it.
Key priorities
Test paid compatible jobs and record technician time, travel, sourcing, parts, tokens, callbacks and collection. The completed-job mix is not measured local demand. Smart-key and ignition tasks may consume more effort than a lockout while using the same van calendar. Validate average and peak scheduling before relying on the slot ceiling. The proposed first operating month is January 2027. The owner should confirm service readiness, paid staffing and available cash before opening the calendar.
Financial highlights
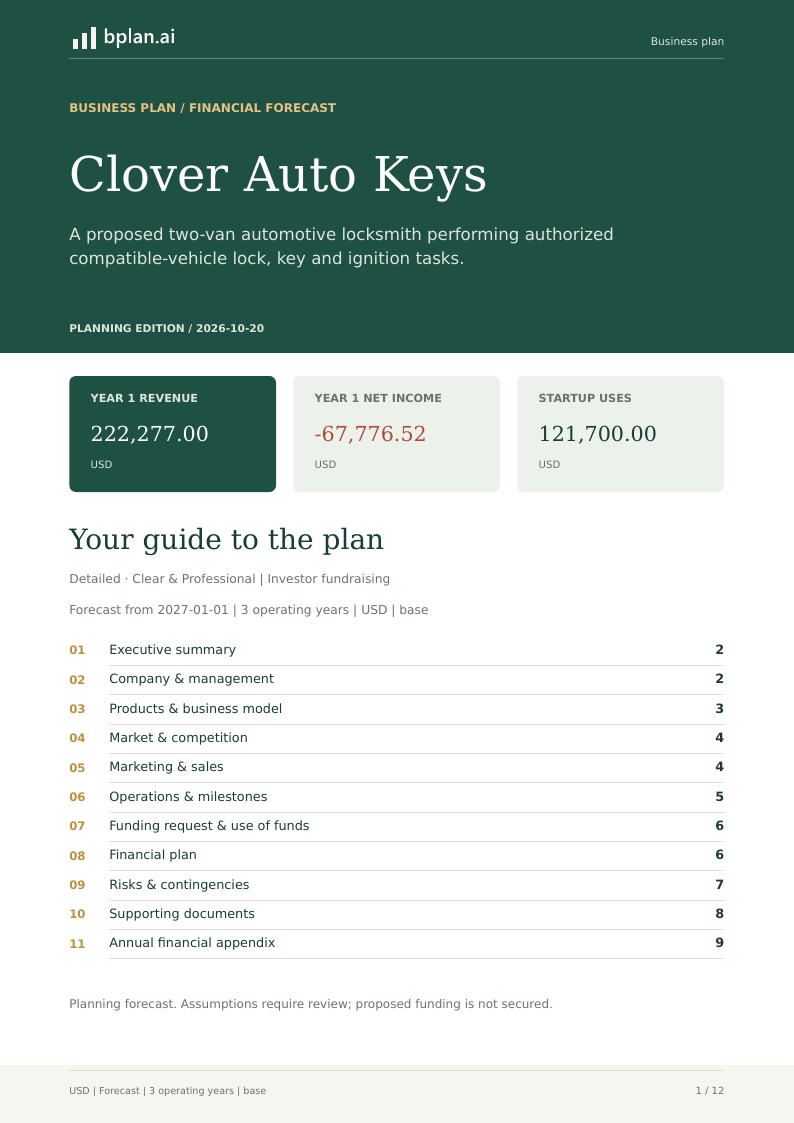
The proposal requires $225,000.00 in equity. Launch spending is $121,700.00, leaving $103,300.00 in opening cash. Year 1 revenue is $222,277.00 and net income is -$67,776.52. The first-year operating shortfall means sales do not yet cover the paid team and overhead. Funding provides time to establish demand; it does not remove that shortfall. The initial project outlay is not recovered within three operating years.
02 / THE PLAN
Company & management
Clover Auto Keys will operate as an independent service business. The working owner will control scope, staffing, commercial terms and weekly cash decisions; legal formation and the ownership agreement must be completed before trading.
Company background
Clover Auto Keys is a fictional Nashville mobile automotive service with two owned used vans and secure storage/dispatch space. The selected scope is mainstream compatible vehicles within a compact proposed territory. No customer access authorization, actual license, dealer relationship or fleet contract is supplied. The operating boundary must be verified against real equipment, qualifications and local conditions.
Ownership & management
The proposed owner contribution is $225,000.00 and covers all modeled equity. No external equity is included. The owner is also paid for an operating role. Legal ownership, professional eligibility and distribution terms must be verified before trading.
Team & responsibilities
Two paid automotive locksmith technicians operate the vans. Owner dispatch is paid for fractional coordination coverage and creates no third technician. The monthly owner-management budget pays for that part-time coverage; it does not add another technician. The source’s average job slots still need real task/travel logs; they are not proof of a fully deliverable maximum calendar. Auto key techs: 2 × $5,000.00 monthly, plus a 15% employer-cost allowance; Owner dispatch: 1 × $1,833.33 monthly, plus a 15% employer-cost allowance. A weekly roster must cover delivery, preparation, travel, administration, leave and absence. The owner’s salary appears once in payroll; contributed time is not an additional cash contribution.
03 / THE PLAN
Products & business model
The offer is limited to work the team can define, price and deliver consistently. Each agreement should identify the buyer, included tasks, access requirements, deliverables, acceptance and payment terms.
Products & services
The five flat-job categories are vehicle lockout, mechanical key replacement, transponder key replacement, smart key replacement and ignition lock repair. Selected prices assume a defined compatible task, not unlimited work on any vehicle. Key/fob/lock parts, fuel and purchased code/token services are direct costs. Durable programmers and cutters are launch assets rather than repeated per-job purchases.
Pricing & revenue streams
176 available completed job units per month × 55% utilization = 96.8 sold units before ramp and seasonality. This shared capacity pool allocates completed work. 5 mutually exclusive service shares allocate that pool once. Each price is per completed job. The 3-month ramp, 6% annual requested-volume growth, normalized monthly seasonality and 2% annual price growth are illustrative. Fractional units are expected monthly averages, not partial completed customer assignments. Actual scheduling, completed work and collections still need validation. Vehicle lockout: 25% of the shared capacity at $85.00 per completed job. Mechanical keys: 15% of the shared capacity at $150.00 per completed job. Transponders: 30% of the shared capacity at $225.00 per completed job. Smart keys: 20% of the shared capacity at $350.00 per completed job. Ignition repair: 10% of the shared capacity at $275.00 per completed job. Fees exclude customer sales tax. Confirm scope and any exceptional materials before accepting a fixed price.
Customer value
The proposed value is verified customer authority, equipment fit and a clearly accepted task. No promise of universal vehicle access, successful programming or damage-free ignition repair is made. Establish compatibility and limits before reserving a slot. An unsuitable vehicle or task requires referral or a new assessed scope, rather than an assumed premium sale.
04 / THE PLAN
Market & competition
The initial market is the specific buyer and buying occasion described below. The launch should be justified by paid work in a practical service area, rather than by applying a market-share percentage to a broad industry estimate.
Target customers
Vehicle owners and authorized agents with a mainstream compatible vehicle, a defined task and an agreed payer. Confirm who commissions the work, who supplies access or records and who authorizes payment. Keep the initial territory small enough to support the promised response and delivery time.
Demand & validation
Test paid compatible jobs and record technician time, travel, sourcing, parts, tokens, callbacks and collection. The completed-job mix is not measured local demand. Smart-key and ignition tasks may consume more effort than a lockout while using the same van calendar. Validate average and peak scheduling before relying on the slot ceiling.
Competition & positioning
Alternatives include another automotive locksmith, a suitable vehicle dealer or an existing fleet key provider. Compare vehicle compatibility, included parts, access authority, travel and completion terms. No universal dealer-price saving or local provider ranking is asserted. A cheaper starting fee can cover a different blank, fob or programming boundary.
05 / THE PLAN
Marketing & sales
The acquisition process should bring in work that fits the team and produces collected contribution after delivery costs. Track qualified opportunities, accepted quotes, completed work and cash received as separate steps.
Customer acquisition
Owner dispatch would use accurate local service information, suitable introductions and referrals after accepted work. Fixed advertising is separate from activity-linked referral fees and launch services. Screen requester authority, location and compatibility early. Do not claim real credentials, dealer authorization, completed vehicle results or continuous emergency coverage without evidence.
Sales process
Confirm the authorized requester and vehicle/task compatibility, agree included parts and work, approve changes and document acceptance before collection or invoice. Most assumed payments are immediate, with a small invoice share reflected in blended days. No separate key retail stream, prepaid fleet account or uncontracted reimbursement funds the operation.
Retention & measurement
Keep appropriate task, authorization, compatibility and callback records under controlled access. A warranty revisit is different from a new paid job. Additional vehicle or key work requires appropriate fresh authority. A repeat fleet request does not become a guaranteed subscription or a permission to reuse sensitive vehicle/customer information.
06 / THE PLAN
Operations & milestones
Delivery must fit the paid team’s hours, equipment and service window. Work should enter the calendar only after scope, competence, access and required resources are confirmed.
Facilities & resources
Launch assets include two vans, installed benches, programmers/diagnostic kits, key cutters, durable tools, payment hardware and secure storage. Only physical parts and the selected fuel allowance enter goods holding; purchased codes/tokens are services. Software updates remain recurring. The refundable deposit and unquoted equipment access/training requirements are excluded until verified. The launch asset budget is Two used cargo vans: $60,000.00; Installed van benches and storage: $14,000.00; Two programmers and diagnostic kits: $16,000.00; Two key cutting machines: $8,000.00; Durable entry and decoding tools: $5,000.00; Computers and payment hardware: $3,000.00; Storage furniture and security: $2,000.00.
Service delivery
Qualify authority and task fit, confirm a suitable technician/tool set, agree scope, schedule the same vans, document completed work and reconcile parts/tokens and payment. This is a commercial outline, not a vehicle-entry or programming procedure. Travel, incompatibility and callbacks consume paid technician time. Average job slots do not certify every individual assignment or the maximum daily schedule.
Launch & development milestones
Verify permissions and competent service scope, insurer terms, compatible tools/parts access, vehicle condition and storage terms. Complete paid trials across the selected categories with full effort and callback logs. Confirm owner reserve before committing equipment purchases. No license, completed programming trial, standing fleet contract or funded launch is presented as achieved.
07 / THE PLAN
Funding request & use of funds
All proposed equity must be available before launch payments. The funding plan separates equipment and setup spending from the cash reserve needed to support operations.
Use of funds
Launch spending totals $121,700.00: $108,000.00 for assets, $8,500.00 for expensed setup and $5,200.00 for opening inventory. Setup covers an allowance for formation, professional preparation, training and launch work. Refundable premises deposits and additional site work are excluded until scoped quotes are available.
Sources of funding
Total proposed equity is $225,000.00, entirely from the owner. This contribution is uncommitted. No external investors or borrowing are included, and financing receipts are separate from earned revenue.
Owner contribution
The owner must confirm the availability and transfer date of the $225,000.00 contribution. Salary pays for the owner’s continuing operating work. The company still needs cash for payroll, equipment and supplier invoices, even when the owner contributes additional time.
Funding request
No external equity is requested. Receiving the proposed owner equity leaves $103,300.00 of opening cash and a forecast funding gap of $0.00. Confirm the owner's available funds and transfer date before committing launch payments.
08 / THE PLAN
Financial plan
The forecast covers January 2027–December 2029 in USD, with launch spending reported separately. Its usefulness depends on the service mix, fee, staffing cost and collection terms below.
Forecast assumptions
176 available completed job units per month × 55% utilization = 96.8 sold units before ramp and seasonality. This shared capacity pool allocates completed work. 5 mutually exclusive service shares allocate that pool once. Each price is per completed job. The 3-month ramp, 6% annual requested-volume growth, normalized monthly seasonality and 2% annual price growth are illustrative. Fractional units are expected monthly averages, not partial completed customer assignments. Actual scheduling, completed work and collections still need validation. Direct costs are 21.5% of net fees. Only purchased materials enter inventory; outside services are not stocked. Salaries are operating expenses, outside the direct-cost ratio. Salaries and fixed overhead grow 3% annually. Collections take 3 days, supplier payments 0 days and inventory coverage 24.2 days. The 21% flat income-tax provision and 15% employer-cost allowance are simplified planning inputs.
Financial outlook
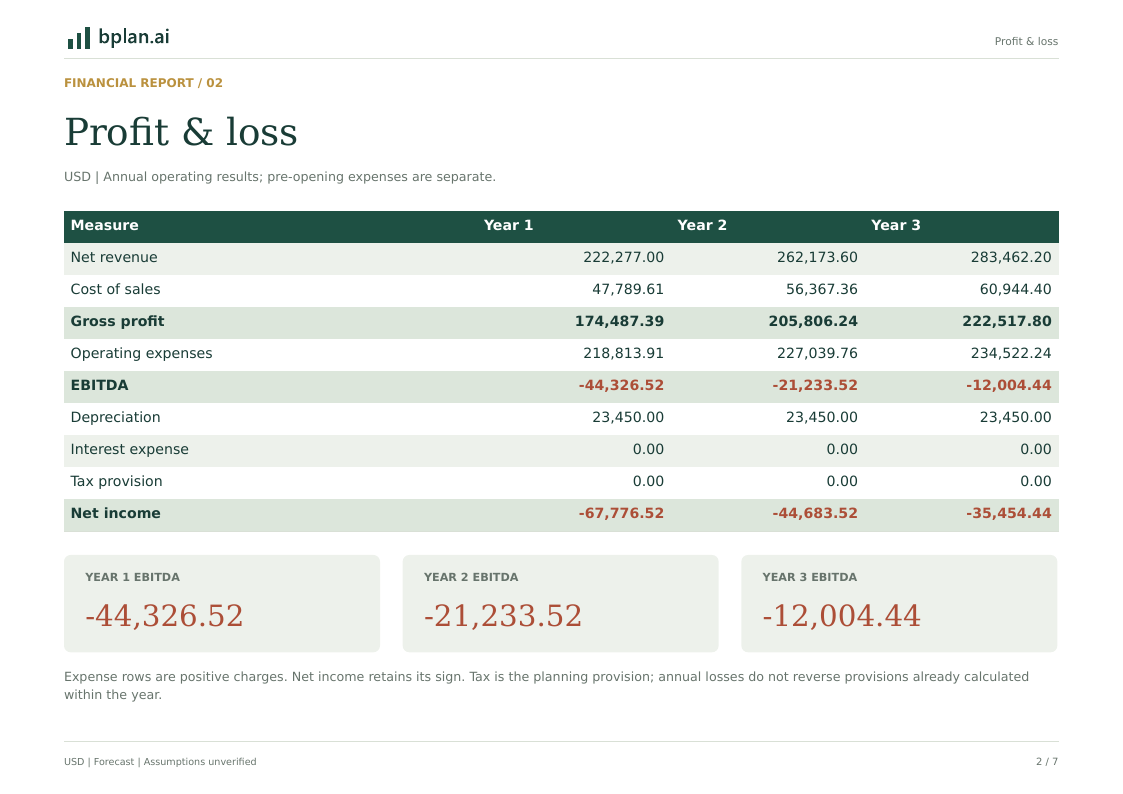
Year 1: revenue $222,277.00, EBITDA -$44,326.52, net income -$67,776.52 and closing cash $58,892.72. Year 2: revenue $262,173.60, EBITDA -$21,233.52, net income -$44,683.52 and closing cash $37,230.39. Year 3: revenue $283,462.20, EBITDA -$12,004.44, net income -$35,454.44 and closing cash $24,762.34. The first-year operating shortfall means sales do not yet cover the paid team and overhead. Funding provides time to establish demand; it does not remove that shortfall. EBITDA excludes depreciation, interest and income tax; net income includes depreciation and the tax provision.
Cash needs & financial resilience
The lowest forecast cash balance is $24,762.34, and the funding gap is $0.00. Positive monthly operating EBITDA is not reached within the three years. The initial project outlay is not recovered within three operating years. Cash differs from profit because of equipment spending, depreciation, collection delays and financing. Review the monthly low point before committing the reserve.
Debt & repayment
No debt or investor distributions are included. Any borrowing option needs an amount, draw date, interest rate and repayment schedule before its affordability can be assessed. Pre-tax project payback measures recovery of the operating investment; it is not a promised dividend, investor return or financing approval.
09 / THE PLAN
Risks & contingencies
The main exposure is committing paid resources before collected sales justify them. The owner should use the service-specific risks below to decide when to narrow the offer, defer spending or stop.
Key risks
The initial owner-only reserve failed the cash forecast. The explicit revised owner proposal adds reserve while retaining prices, expected jobs, salaries, all annual losses and lack of payback. Parts compatibility, token access, callbacks, damage and dead travel can worsen the result. More proposed funding does not demonstrate profitable demand or suitable vehicle access.
Contingency actions
Keep the initial inputs and cash shortfall beside the revised proposed owner reserve. Verify actual cash and tool/vehicle fit before taking commitments. Test fewer paid jobs, longer travel and higher parts/callback costs with both technicians retained. Narrow compatibility or delay opening instead of treating owner dispatch as unpaid or inventing guaranteed fleet work.
10 / THE PLAN
Supporting documents
The launch decision needs commercial evidence as well as a forecast. Maintain an organized working file so that costs, commitments and delivery capacity can be reviewed before money is spent.
Available supporting information
The operating proposal defines the customer, service boundary, paid roles, launch assets and collection terms. The accompanying annual financial statements set out earnings, cash flow and the balance sheet for the three-year period. All funding remains a proposal; the business is at the prelaunch stage.
Documents to obtain
Actual permissions and authorization terms, qualified technicians, suitable insurer scope, compatible tool/software/code and parts terms, storage/deposit quotes, vehicle checks, paid job/time/collection records and committed owner funding remain outstanding. No universal access capability, guaranteed result or secured finance is supplied. Record the actual fee, total delivery effort and date of payment for each trial assignment. Update the forecast and funding decision when quotes, commitments or measured results change a material assumption.
02 / THE FINANCIAL MODEL
How this business earns and uses cash.
176 available completed job units per month × 55% utilization = 96.8 sold units before ramp and seasonality. This shared capacity pool allocates completed work. 5 mutually exclusive service shares allocate that pool once. Each price is per completed job. The 3-month ramp, 6% annual requested-volume growth, normalized monthly seasonality and 2% annual price growth are illustrative. Fractional units are expected monthly averages, not partial completed customer assignments. Actual scheduling, completed work and collections still need validation.
The forecast covers three operating years, with prelaunch spending shown separately. Fees, workload, staffing and collection terms determine whether the business can cover its commitments and preserve cash.
| Service | Pool allocation | Base price | Billing unit |
|---|---|---|---|
| Vehicle lockout | 25% | $85.00 | One completed job |
| Mechanical keys | 15% | $150.00 | One completed job |
| Transponders | 30% | $225.00 | One completed job |
| Smart keys | 20% | $350.00 | One completed job |
| Ignition repair | 10% | $275.00 | One completed job |
| Cost or paid role | Base input | Treatment |
|---|---|---|
| Auto key techs | $10,000.00/month before employer costs | Paid role; 15% employer allowance |
| Owner dispatch | $1,833.33/month before employer costs | Paid role; 15% employer allowance |
| Secure storage and dispatch base | $900.00/month before employer costs | Operating expense |
| Vehicle liability and tools cover | $700.00/month before employer costs | Operating expense |
| Software updates and communications | $350.00/month before employer costs | Operating expense |
| Utilities and office supplies | $150.00/month before employer costs | Operating expense |
| Vehicle and equipment maintenance | $300.00/month before employer costs | Operating expense |
| Registration and compliance admin | $100.00/month before employer costs | Operating expense |
| Bookkeeping and professional | $300.00/month before employer costs | Operating expense |
| Local advertising and website | $900.00/month before employer costs | Operating expense |
| Payment processing | 2.5% of net fees | Operating expense |
| Callbacks and damage allowance | 1% of net fees | Operating expense |
| Referral fees | 1.5% of net fees | Operating expense |
| Input | Case value |
|---|---|
| Collection delay | 3 days |
| Inventory / supplier payment | 24.2 days / 0 days |
| Direct costs | 21.5% of net fees |
| Price / requested-demand growth | 2% / 6% annually |
| Salary and fixed-cost growth | 3% annually |
| Income-tax provision | 21% simplified provision |
| Proposed owner equity | $225,000.00 |
| Proposed external equity | $0.00 |
| Prelaunch setup | $8,500.00 |
Direct costs cover 21.5% of fees and exclude the paid roles already shown in operating expenses. The material share uses the purchased-stock ledger; outside services remain direct expenses. All-in customer prices are not duplicated as extra parts or product revenue.
What the forecast shows
The forecast shows a net loss in Year 1, Year 2, Year 3. Net income includes depreciation and the monthly tax provision. EBITDA excludes depreciation, interest and tax; cash also reflects assets, working capital and financing.
| Measure | Year 1 · 2027 | Year 2 · 2028 | Year 3 · 2029 |
|---|---|---|---|
| Revenue | $222,277.00 | $262,173.60 | $283,462.20 |
| Cost of sales | $47,789.61 | $56,367.36 | $60,944.40 |
| Gross profit | $174,487.39 | $205,806.24 | $222,517.80 |
| Operating expenses | $218,813.91 | $227,039.76 | $234,522.24 |
| EBITDA | -$44,326.52 | -$21,233.52 | -$12,004.44 |
| Depreciation | $23,450.00 | $23,450.00 | $23,450.00 |
| Interest | $0.00 | $0.00 | $0.00 |
| Tax provision | $0.00 | $0.00 | $0.00 |
| Net income | -$67,776.52 | -$44,683.52 | -$35,454.44 |
| Measure | Year 1 · 2027 | Year 2 · 2028 | Year 3 · 2029 |
|---|---|---|---|
| Opening cash | $103,300.00 | $58,892.72 | $37,230.39 |
| Customer collections | $220,256.30 | $262,009.52 | $283,284.79 |
| Supplier payments | $45,849.67 | $56,632.09 | $61,230.60 |
| Operating expenses paid | $218,813.91 | $227,039.76 | $234,522.24 |
| Interest paid | $0.00 | $0.00 | $0.00 |
| Tax provision paid | $0.00 | $0.00 | $0.00 |
| Operating cash flow | -$44,407.28 | -$21,662.33 | -$12,468.05 |
| Investing cash flow | $0.00 | $0.00 | $0.00 |
| Financing cash flow | $0.00 | $0.00 | $0.00 |
| Net change | -$44,407.28 | -$21,662.33 | -$12,468.05 |
| Closing cash | $58,892.72 | $37,230.39 | $24,762.34 |
| Measure | Year 1 · 2027 | Year 2 · 2028 | Year 3 · 2029 |
|---|---|---|---|
| Cash | $58,892.72 | $37,230.39 | $24,762.34 |
| Receivables | $2,020.70 | $2,184.78 | $2,362.19 |
| Inventory | $3,260.06 | $3,524.79 | $3,810.99 |
| Net fixed assets | $84,550.00 | $61,100.00 | $37,650.00 |
| Assets | $148,723.48 | $104,039.96 | $68,585.52 |
| Payables | $0.00 | $0.00 | $0.00 |
| Loan balance | $0.00 | $0.00 | $0.00 |
| Liabilities | $0.00 | $0.00 | $0.00 |
| Equity and retained earnings | $148,723.48 | $104,039.96 | $68,585.52 |
| Reconciliation difference | $0.00 | $0.00 | $0.00 |
Launch spending is $121,700.00; opening cash is $103,300.00 after all proposed equity. The unfunded gap is $0.00. Pre-tax project payback is not reached within 36 months. Project recovery is not an investor distribution.
Inspect the actual report
Planning limits and qualifications
Planning model, not audited accounts or tax advice. Revenue is invoiced as earned; monthly subscriptions only. Annual prepayments, refundable deposits, milestone invoices, unbilled contract assets, customer taxes, seller settlements, capitalized interest and tax-loss carryforwards are not modeled.
Collection and supplier terms use 30-day monthly interpolation. Inventory purchases and non-stock direct costs use supplier terms; operating costs, setup costs, taxes and opening stock are paid immediately. Stock coverage applies only to linked goods costs. Production stock is tracked separately at unit cost.
Fictional editorial scenario. Prices, workload, wages, costs and financing are illustrative planning inputs, not current quotes, measured local averages or actual company results.
Source two-van completed-job format retained for 36 months: 176 monthly job slots at 55%, original five shares/fees and fixed paid technicians with 0.4 owner dispatch. Three-month ramp and 6% requested growth replace utilization steps; slot feasibility still needs measured task/travel logs. Source 23 effective inventory days become 24.2 physical fuel/parts days, weighted once. Tokens are purchased services, not stock. Setup paid once, deposit excluded. Simplified 21% tax, 15% employee allowance, 2% fees and 3% fixed costs.
A 15% illustrative employer allowance is added to paid salaries. The flat 21% native tax provision is a simplified planning input, not an entity or personal tax opinion. Customer sales-tax receipts/remittances and owner distributions are outside this scenario.
All equity is proposed, uncommitted month-0 cash. No debt is modeled. Opening cash is a reserve, not an extra startup expense. Asset/setup/insurance/premises allowances need scoped quotes; refundable premises deposits and site-specific additional works are excluded.
03 / ACTUAL TEN-SLIDE PITCH
A focused funding conversation.
All ten pages of the delivered PDF. Buyer demand, team roles and funding remain proposed.
Clover Auto Keys
Every slide is available in the complete ten-slide PDF. The full slide text follows.
Read the complete slide outline
1. Clover Auto Keys
Vehicle keys within a clear scope.
Fictional prelaunch
2. Compatibility takes time.
Available units → completed work → fees
Demand and completion are assumptions.
Paid work will test time and margin.
3. A clear scope. A controlled delivery process.
Agree
Schedule
Deliver
Collect
One agreed scope. Documented acceptance.
4. Start with a reachable buying occasion.
Vehicle owners
An authorized key task
Authorized agents
A compatible vehicle job
Schematic; buyers and area to validate.
5. Defined billing units. One shared service mix.
Mix
Vehicle lockout 25%
85
Mechanical keys 15%
150
Transponders 30%
225
Smart keys 20%
350
Ignition repair 10%
275
USD / completed job.
6. Compete on the job and the commercial terms.
Possible alternatives
Check before booking
Another auto locksmith
Authority and fit
Suitable vehicle dealer
Parts and tool access
Existing fleet key service
Full job effort
Compare equivalent work and written terms.
7. Fund the launch. Keep a reserve.
225,000.00
Proposed equity
121,700.00
Launch uses
103,300.00
Opening cash
Year 1 net loss: USD -67,776.52
Minimum cash: USD 24,762.34
8. Proposed team. Clear delivery responsibilities.
Monthly base pay
Auto key techs
10,000.00
Owner dispatch
1,833.33
Paid technicians share the same van calendars.
9. Prove the job economics before adding capacity.
Paid jobs
Time
Cash margin
Prelaunch. These are the next tests.
10. Proposed owner equity.
USD 225,000.00
External equity requested: USD 0.00
Terms and funding remain uncommitted.
Project payback: not reached within 36 months
KEEP THE COMPLETE EXAMPLE
Three matching documents.
Free fictional sample PDFs. Actual page counts and byte sizes are shown below.
Business plan
12 pages · A4 portrait
96,543 bytes · PDF
Financial report
7 pages · A4 landscape
62,543 bytes · PDF
Pitch deck
10 pages · 16:9 landscape
47,186 bytes · PDF
Build around your own decisions.
Use your own service boundary, actual quotes, paid staffing and payment terms. Review every assumption before preparing your own package.
Create a plan like this ↗